The SBA 504 Loan Program is becoming even more attractive for a broader group of small businesses.
For fiscal year 2027, the U.S. Small Business Administration is continuing its 504 fee waivers for manufacturers and expanding the waivers to eligible businesses supporting the food supply chain and businesses located in rural areas. The change applies to qualifying 504 loans approved from October 1, 2026 through September 30, 2027.
Under the new fee structure, qualifying borrowers will have both the upfront SBA guaranty fee and the annual SBA service fee waived. The waiver applies to eligible:
- Manufacturers within NAICS sectors 31, 32 and 33;
- Food supply chain businesses within the NAICS codes identified by SBA;
- Businesses located in rural areas.
This applies to both new money requests (construction, real estate purchase, equipment, etc.) and 504 refinance requests (straight debt refinance and refinance with cashout).
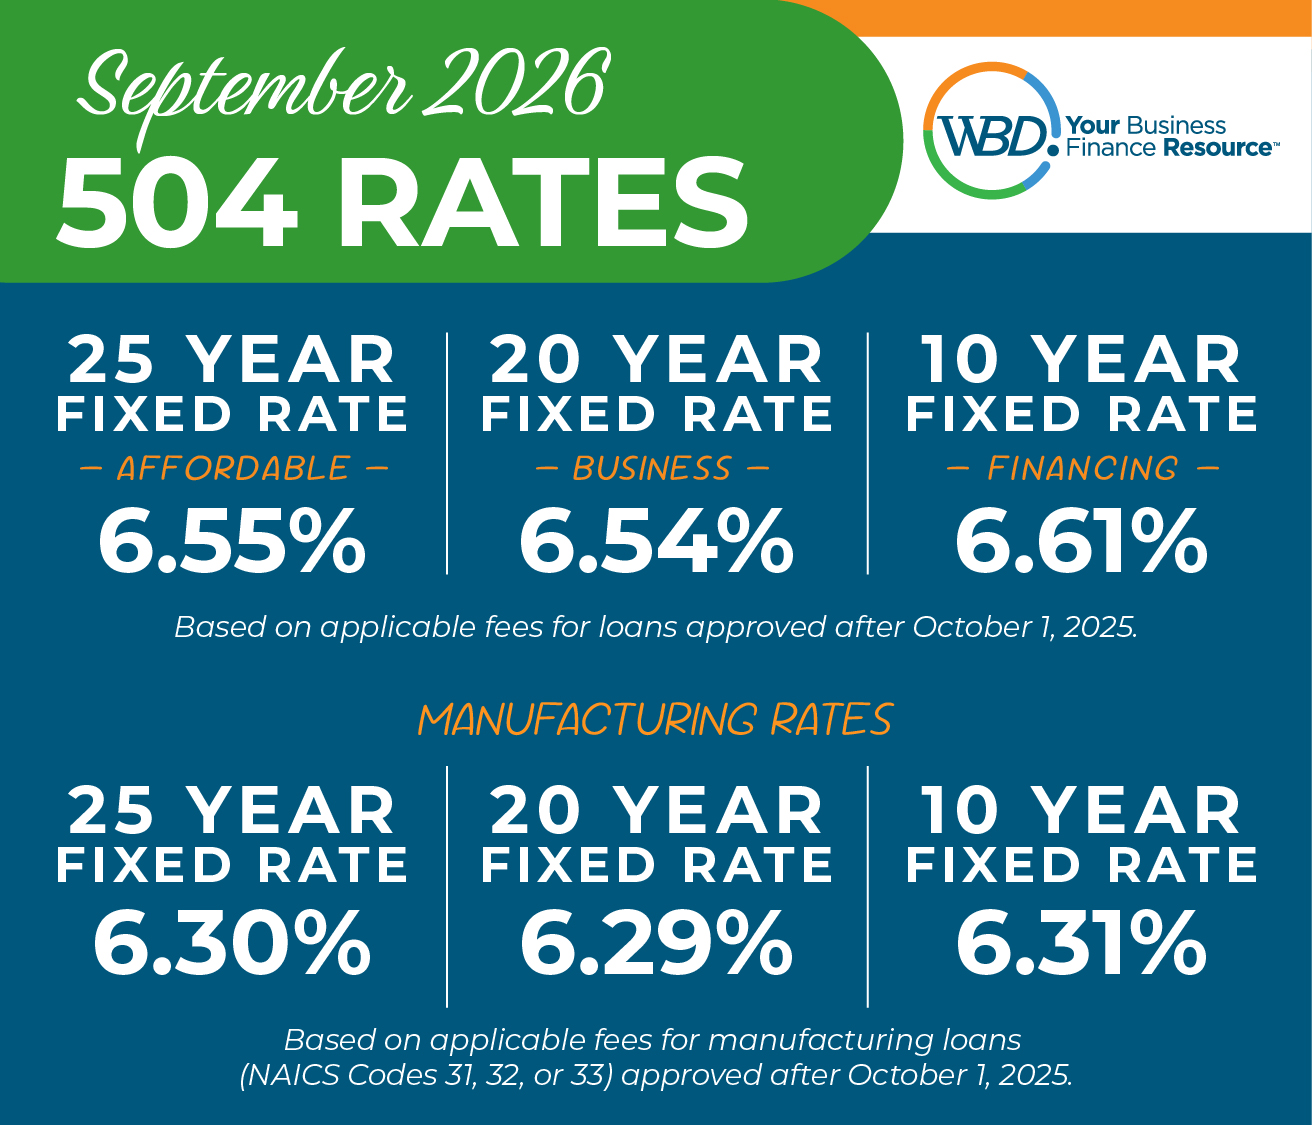
This expansion can create meaningful long-term savings for eligible borrowers by reducing the fees incorporated into the 504 debenture and ongoing loan payments. For most eligible loans, the fee waivers are expected to reduce the borrower’s 504 effective rate by approximately 25 basis points.
For lenders, the expanded waiver creates an important opportunity to revisit upcoming projects and existing relationships. Potential candidates may include agricultural operations, food processors, wholesalers, refrigerated warehousing and transportation businesses, grocery-related businesses, and other qualifying participants in the food supply chain. Certain transportation NAICS codes are limited to refrigerated and frozen trucking or the transportation of farm products, grain products and livestock, so confirming the borrower’s specific NAICS classification will be important. NAICS classification will be determined by the most recent business tax return.
The rural business expansion may be particularly impactful for lenders throughout Wisconsin and Minnesota. Businesses do not need to be manufacturers or part of the food supply chain to qualify under the rural provision, provided the project meets SBA’s rural-area requirements. Eligibility is based on the location of the project being financed.